Credit card sign-up bonus math — what a $750 offer is worth
How to weigh a credit card sign-up bonus against the minimum spend, annual fee, and year-one rewards — and spot when a bigger bonus is the worse deal.
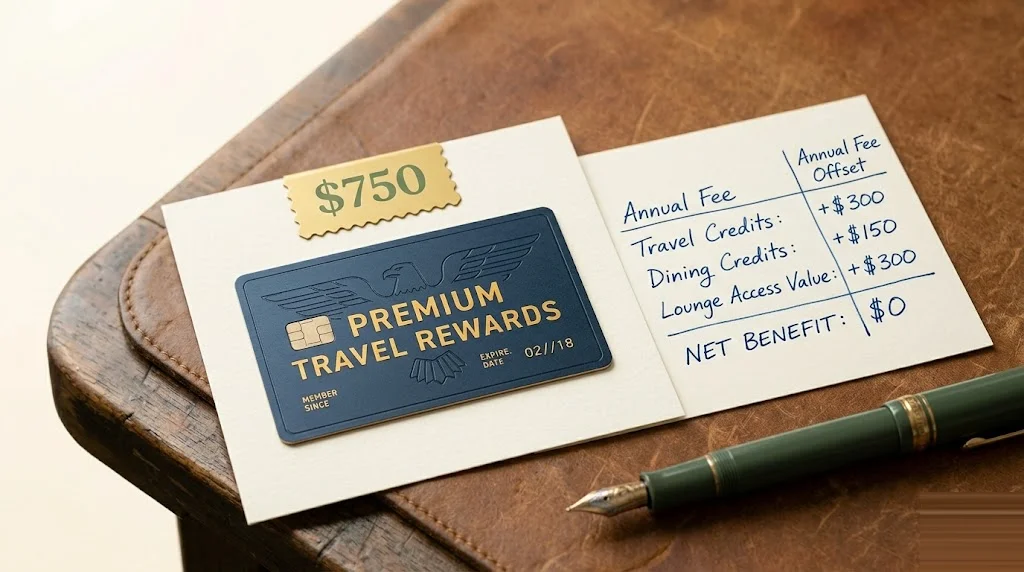
The dominant marketing message in US credit card advertising for the last decade has been the sign-up bonus — a one-time award, typically denominated in points, miles, or cash, paid to a new cardholder who meets a minimum spending requirement in the first few months of card ownership. The numbers have escalated over time. A $200 sign-up bonus was generous in 2015; $500 is standard in 2026; the premium products advertise bonuses of $750, $900, sometimes $1,200 or higher in equivalent-cash terms. The marketing focuses on the headline number because the headline number is the easiest piece of the math to communicate. The headline number is also frequently the least relevant piece of the math for the applicant making the decision.
This guide walks through what a sign-up bonus is actually worth to a specific applicant once the minimum spending requirement, the conservative point valuation, the year-one ongoing rewards, the annual fee, and the bonus-eligibility risk are all factored in. The conclusion the math returns is that a $750 headline bonus on the wrong card for a given household can be worth less in real cash terms than a $400 bonus on the right card, and the difference can run into the hundreds of dollars per year.
Minimum spend requirement mechanics — what counts and what does not
Every meaningful sign-up bonus comes attached to a minimum spending requirement, usually shortened to MSR in the personal finance communities. The MSR specifies the amount the cardholder must charge to the card in a defined time window from the account-opening date to qualify for the bonus. The typical structure: spend $4,000 within three months of account opening to earn the bonus. The specific dollar amount and the time window vary by card and by the size of the bonus; larger bonuses come with proportionally larger MSRs.
The arithmetic the applicant has to do upfront is whether the MSR is achievable given the household’s normal spending pattern. A household that normally puts $1,200 a month on the card hitting a $4,000 MSR in three months is comfortable. A household that normally puts $800 a month is short by $1,600 over the window and has to either accelerate spending into the window (frequently by prepaying expenses like insurance premiums or annual subscriptions) or accept that the bonus will not trigger. Spending money the household would not otherwise have spent in order to hit an MSR is value-destroying; the spending is real cash out of the household, the bonus is fixed, and the net is reliably negative.
The mechanics of what counts toward MSR are mostly straightforward but have one common pitfall. Net purchases count: groceries, gas, restaurants, travel, online shopping, subscriptions, almost any merchant-coded transaction. Refunds and returns reduce the count; a $200 return after a $200 purchase nets to zero against the MSR. Cash advances, balance transfers, fees, and interest charges do not count. The pitfall: certain merchant categories the cardholder thinks of as normal spending may not count if they post as cash-equivalent (gift card purchases at certain merchants, money order purchases, certain payment processor transactions). Reviewing the cardmember agreement for the specific MSR exclusions before relying on a marginal transaction to push over the threshold is the defensive move.
The time-window mechanics matter as well. The window starts on the account opening date, not the card receipt date. An applicant approved on March 1 has until June 1 to hit the MSR, regardless of whether the physical card arrived on March 8 or March 15. Charges before the card arrives — if the applicant added the card to a mobile wallet that processed transactions before the physical card was in hand, or if the applicant arranged a manual key-in on a recurring bill — count toward the MSR window.
Effective bonus value — applying the conservative valuation
The headline bonus number is denominated in the card’s specific reward currency. Translating it into a comparable dollar figure requires applying the appropriate conservative point valuation — the same exercise covered in the companion guide on cash back versus travel rewards but applied at the bonus stage.
A few examples to make the framework concrete:
A Chase Sapphire Preferred advertised “60,000 bonus points after $4,000 spend” is denominated in Chase Ultimate Rewards points. At the conservative household valuation of 1.6 cents per point, the bonus is worth $960 — well above the $600 headline if the marketing converted points to dollars at the portal 1.0-cent rate. The applicant who actually redeems through the Chase Travel portal at 1.25 cents (Preferred tier) gets $750; the applicant who transfers to Hyatt for hotel nights gets closer to $1,200 to $1,500; the applicant who redeems for cash back at 1.0 cent gets $600. The “actual” value depends on the actual redemption.
An American Express Gold Card advertised “60,000 Membership Rewards points after $6,000 spend” is denominated in Membership Rewards. At the conservative household valuation of 1.5 cents per point, the bonus is worth $900. The applicant who uses Pay With Points at 1.0 cent gets $600. The transferred-to-ANA-for-business-class applicant gets several thousand dollars in equivalent cash; but the math is irrelevant for the typical applicant.
A Capital One Venture X advertised “75,000 miles after $4,000 spend” is denominated in Capital One miles. At the conservative valuation of 1.3 cents, the bonus is worth $975. At the Capital One Travel portal floor of 1.0 cent, $750.
A flat-rate cash back card advertised “$200 cash back after $1,500 spend” requires no valuation translation — the $200 is the $200.
The lesson is that direct comparison of the headline bonus across cards in different reward currencies is misleading. The right comparison is the conservative-valuation cash equivalent, calculated against the realistic redemption pattern the specific applicant will use.
The year-one yield calculation
The year-one yield is the bonus value plus the ongoing rewards earned in the first twelve months, minus the annual fee. The calculation produces a single number that captures the full first-year economics of the card and is comparable across cards.
For the Chase Sapphire Preferred (60,000 point bonus at 1.6 cents = $960, $95 annual fee), with a household spending $40,000 per year in the distribution covered in the cash back versus travel guide:
- Year-one ongoing rewards: approximately $1,048 (the calculation from the cash back versus travel guide).
- Bonus value: $960.
- Annual fee: -$95.
- Year-one yield: $1,913.
For the same household on a Citi Double Cash (no bonus baseline assumption: $200 cash back after $1,500 spend, $0 annual fee):
- Year-one ongoing rewards: $800.
- Bonus value: $200.
- Annual fee: $0.
- Year-one yield: $1,000.
For the same household on an American Express Gold (60,000 point bonus at 1.5 cents = $900, $325 annual fee, the household uses the $120 dining credit and the $120 Uber credit fully):
- Year-one ongoing rewards: approximately $1,180 (4x on dining and groceries at this distribution).
- Bonus value: $900.
- Annual fee: -$325.
- Statement credits captured: +$240.
- Year-one yield: $1,995.
The year-one yield calculation often inverts the headline ranking. A card with a smaller advertised bonus but stronger ongoing rewards and a lower annual fee can outperform a flashier card; a card with a large bonus but a premium annual fee and weak ongoing rewards for this specific household can underperform. The year-one yield is the metric that internalizes all of these effects into a single comparable number.
A second important version of the calculation is the year-two yield. After the bonus is captured and the year-one statement credits are spent, the card reduces to its ongoing rewards minus annual fee. A card that wins on year-one yield but loses on year-two yield is a candidate for downgrade-or-close at the end of the first year, an action that is mechanically straightforward but rarely planned at the time of application. A downgrade is a product change, which never earns a new bonus and never resets your eligibility clock — so it manages the fee without affecting whether you can chase the next welcome offer.
When a sign-up bonus is a trap
A large headline bonus is occasionally a marketing signal for a card with structural problems that erase the bonus value over time. The patterns:
The card with a bonus on a card whose ongoing rewards do not match the household’s spending. The Chase Ink Business Preferred has a substantial bonus (currently 90,000 points after $8,000 spend in 3 months) on a card that earns 3x in narrow categories (shipping, internet, travel, advertising) that do not fit most personal-spending households. A consumer applicant who hits the MSR by accelerating personal spending into the card captures the bonus but earns 1x on the ongoing spending, well below the 1.5x or 2x they could earn on a flat-rate card. The bonus is real money; the opportunity cost on the next 12 months of spending is also real money. The net can be negative for the applicant who applied for the bonus without examining the ongoing structure.
The card with a bonus on a card with a high annual fee that does not produce offsetting credits the household will actually use. The American Express Platinum has a substantial bonus (typically 80,000 to 150,000 points depending on offer) and an annual fee of $895. The fee is offset by an array of statement credits (Uber, Resy dining, Lululemon, digital entertainment, hotel and airline incidentals, lounge access) that total far more than the fee in advertised value since the September 2025 refresh. The realized capture rate of these credits varies enormously by household; a household that does not order Uber regularly, does not eat at Resy-listed restaurants, does not pay airline incidental fees, and does not travel through major airports with Centurion lounges will capture perhaps $200 of the more than $3,500 in advertised credits, making the net annual fee $695 against $1,200 of bonus value. The year-one yield is still positive, but the year-two yield is sharply negative without aggressive credit capture, and the card is a candidate to close at the end of year one.
The card with a bonus structure that punishes early closing or downgrade. Most US credit cards do not claw back the bonus if the cardholder closes the account in the first year, but some do — the cardmember agreement specifies the terms, and applicants should read for clawback provisions before applying for a bonus they plan to capture and close. American Express in particular has historically clawed back bonuses on accounts that show “manufactured spending” patterns (large balance immediately paid down with no organic transactions), regardless of the formal closing date. The clawback risk is small for normal organic spending but real for atypical patterns.
Bonus-eligibility risk — the rule lookups required before applying
Before submitting an application primarily for the bonus, two eligibility checks are required to avoid a value-destroying application. Both are covered in detail in the companion guide on issuer velocity rules but the bonus-relevant subsets:
The lifetime bonus eligibility for the specific product, particularly for American Express products. An applicant who held the same American Express product previously and captured the bonus is not eligible for the bonus again. Submitting the application proceeds normally — the card is frequently approved — but the bonus does not post and the bonus-eligibility flag is permanently set on that product. The application is value-destroying because the applicant has captured none of the bonus and has consumed one of their 2-in-90 American Express application slots in the process.
The 24-month bonus cooling-off window for specific Citi products. Citi’s published terms on AAdvantage and ThankYou bonuses require a 24-month window since the last bonus capture on the same product (or, in some cases, the same product family) for the bonus to be eligible. Submitting inside the cooling-off window approves the card but does not pay the bonus.
The defensive posture is to verify lifetime eligibility (for American Express) or cooling-off status (for Citi) before applying. American Express provides an in-application “you are not eligible for the welcome bonus” notice on most products, which the applicant should look for and abort the application if it appears. Citi requires checking the published terms of the specific offer being targeted.
A worked example — the same applicant choosing between two bonuses
Consider Aiden, an applicant with $45,000 in annual credit card spending, $9,000 of which is on dining, who is choosing between two offers: Chase Sapphire Preferred (60,000 points after $4,000 in 3 months, $95 annual fee) versus American Express Gold (60,000 points after $6,000 in 6 months, $325 annual fee, $120 dining credit, $120 Uber credit, $84 Dunkin’ credit).
The bonus-value calculation:
- Chase Sapphire Preferred: 60,000 × 1.6 cents = $960.
- American Express Gold: 60,000 × 1.5 cents = $900.
The MSR achievability:
- Chase: $4,000 in 3 months is $1,333/month, well below Aiden’s $3,750/month average spending.
- American Express: $6,000 in 6 months is $1,000/month, also well below. Both MSRs are easily achievable without any spending acceleration.
The year-one yield:
- Chase Sapphire Preferred: ongoing rewards at this spending profile ≈ $1,200 (3x on dining produces 27,000 points × 1.6 = $432; assume balance of $36,000 × 1.5 effective on bonus-categories-plus-travel) − $95 + $960 = $2,065.
- American Express Gold: ongoing rewards at this dining-heavy profile ≈ $1,400 (4x on dining and groceries) − $325 + $900 + $324 of usable credits if Aiden uses them = $2,299.
The year-one yield favors American Express Gold by approximately $234, primarily because the dining-heavy spending profile takes advantage of the 4x multiplier and Aiden uses Dunkin’ regularly and orders Uber.
The year-two yield (no bonus, all credits assumed usable):
- Chase Sapphire Preferred: $1,200 − $95 = $1,105.
- American Express Gold: $1,400 + $324 credits − $325 = $1,399.
The year-two yield also favors American Express Gold for Aiden’s specific profile.
The decision: apply for American Express Gold first, then the Chase Sapphire Preferred in a subsequent cycle. Both cards are positive year-one and year-two for Aiden; the sequencing question is about velocity rule management (covered in the issuer velocity rules guide) rather than about whether to capture either bonus.
A different applicant with the same total spending but a travel-heavy rather than dining-heavy distribution would reverse the ranking: Chase Sapphire Preferred typically wins for travel spending because of the 2x on travel and the Hyatt transfer pathway. The decision is always specific to the spending profile, not generalizable across applicants.
Sources
- Federal Reserve consumer credit and credit card market data: Federal Reserve — Consumer Credit (G.19).
- CFPB credit card market report (biennial, with bonus structure analysis): CFPB — The Consumer Credit Card Market.
- Card-specific application terms and bonus eligibility: each card’s specific application page on the issuer site. Read the terms section labeled “Welcome Offer” or “Welcome Bonus Eligibility” for lifetime and cooling-off restrictions.
- Conservative point valuations methodology: covered in our cash back versus travel rewards guide.
- Bonus tracking and historical bonus elevation patterns: Doctor of Credit — Best credit card bonuses maintains a current view of which cards are at elevated bonuses vs baseline.
If a number on this page looks off against current issuer behavior, the personal finance communities update faster than this article; let us know via contact and we will reconcile.
Educational content only. finbarrow is an independent editorial publication, not a licensed financial advisor, broker, tax preparer, or attorney. Verify rates and terms with the issuer or relevant regulator. See disclaimers and funding disclosures.