The mega backdoor Roth — how to put $47K into a Roth in one year
The 401(k) after-tax contribution plus in-plan Roth conversion that lets high earners route up to $47,500 into Roth accounts each year.
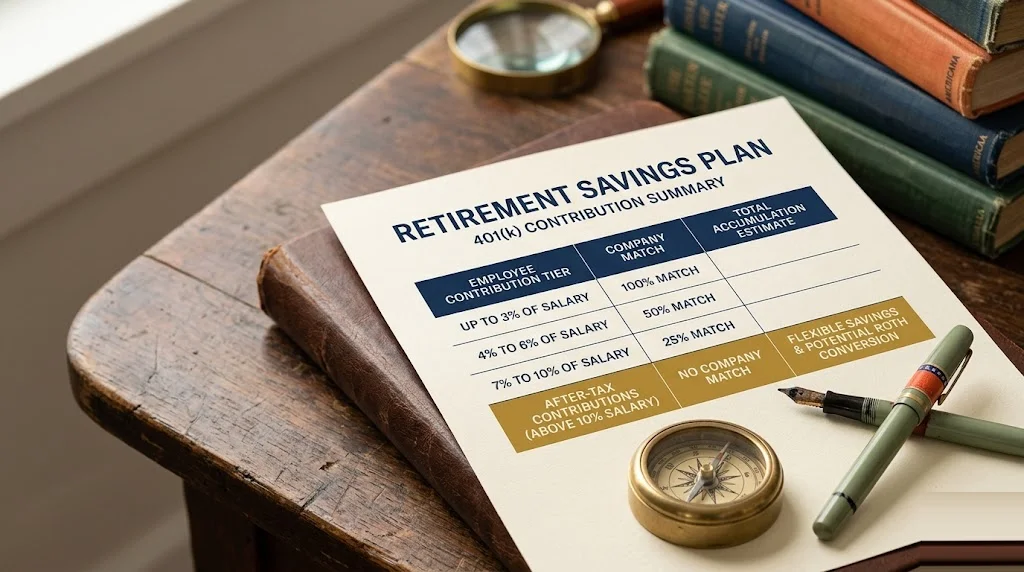
The mega backdoor Roth is the most powerful single tax-optimization move available to high-earning US employees, and one of the least-used. The strategy exploits a specific gap between two Internal Revenue Service limits on 401(k) contributions: the employee elective deferral limit (the headline number most workers know — $24,500 in 2026 for under-50 contributors) and the overall plan contribution limit, which includes employee deferrals plus employer contributions plus a third category called after-tax employee contributions ($72,000 in 2026 for under-50, plus an $8,000 catch-up at 50+).
The gap between the elective deferral plus typical employer match (collectively perhaps $30,000) and the overall limit ($72,000) is the room available for additional after-tax contributions — typically $35,000 to $45,000 per year for an employee at a typical employer match. With the right plan features, those after-tax contributions can be converted to Roth dollars almost immediately, producing a Roth balance that compounds tax-free for the rest of the employee's life, with no income limit and no five-year clock to track on the contributions themselves.The strategy is restricted to employees whose 401(k) plan permits two specific features: after-tax (non-Roth, non-pre-tax) employee contributions, and either an in-plan Roth conversion of those after-tax balances or an in-service withdrawal that allows the employee to roll the after-tax balance to an external Roth Individual Retirement Account. A meaningful share of large US employers (Google, Microsoft, Meta, Amazon, several major banks) have plans that permit both; a meaningful share of employers, including most smaller firms, do not. The first step for any employee curious about the strategy is to verify whether their plan permits it; the rest of the math depends on the answer.
This guide walks through the underlying tax code mechanics, the two specific 401(k) plan features required to execute the strategy, the step-by-step process for an employee whose plan supports it, the tax consequences of each step (including the pro-rata rule on earnings), the common variants offered by different employer plans, and a worked example of a $200,000-a-year employee routing $40,000 of after-tax contributions into a Roth each year for ten years.
The single most important verification before pursuing the strategy: the employee’s 401(k) plan documents must explicitly permit after-tax (non-Roth) employee contributions above the elective deferral limit, and must also permit either in-plan Roth conversions or in-service withdrawals of those after-tax balances. The two features together are uncommon enough that fewer than half of US 401(k) plans support the full strategy. Verifying the plan features in writing — by requesting the Summary Plan Description from the plan administrator — before contributing is the defensive first step.
The tax code mechanics — how the contribution categories fit together
A US 401(k) plan, by Internal Revenue Code Section 415, has an overall annual contribution limit that caps the total of all contributions to a single employee’s account from all sources. In 2026, that overall limit is $72,000 for an employee under age 50, with an $8,000 catch-up contribution available at age 50 and above. The overall limit includes three contribution categories.
The first category is employee elective deferrals — the contributions the employee chooses to make from their paycheck, either pre-tax (traditional 401(k)) or post-tax-but-tax-free-in-retirement (Roth 401(k)). The elective deferral limit is $24,500 in 2026, with an $8,000 catch-up at 50+. The elective deferrals are the contribution category most employees know and use; many employers default new participants into making at least a deferral high enough to capture the full employer match.
The second category is employer contributions. These include the employer match (typically 50% to 100% of the employee’s contribution up to some percentage of salary), the employer profit-sharing contribution (a discretionary contribution some employers make annually), and any other employer-funded contribution. The employer contribution amount varies by plan and by year; a typical full match is in the $5,000 to $15,000 range per year.
The third category is after-tax employee contributions. These are contributions the employee makes from already-taxed income, into a separate “after-tax” subaccount within the 401(k) plan. The after-tax contributions are not the same as Roth contributions: after-tax contributions are after-tax on the way in (no tax deduction), but the earnings on the after-tax balance are taxable on the way out (unlike Roth earnings, which are tax-free). The after-tax contribution category exists in the tax code precisely to fill the gap between the elective deferral limit and the overall annual additions limit under IRC §415 ($72,000 in 2026).
The arithmetic for a typical employee: if employee elective deferrals are $24,500 and employer contributions are $15,000, the combined is $39,500. The overall limit is $72,000. The remaining $32,500 of room is available for after-tax employee contributions. An employee at a more generous employer might have $25,000 of room; an employee at a less generous one might have $40,000 to $45,000.
The after-tax employee contributions are useful on their own — they grow tax-deferred even without conversion, and the after-tax basis is not taxed when eventually withdrawn — but the strategic value of the after-tax bucket comes from converting it to Roth treatment, which is what the mega backdoor Roth strategy accomplishes.
The two plan features required to execute the strategy
The strategy requires two specific 401(k) plan features. Without both, the strategy cannot be executed; the employee whose plan lacks one or both has the option of (a) just making the after-tax contributions and leaving them as after-tax (still useful but less powerful), (b) lobbying the plan sponsor to add the missing features (a real lever at larger employers), or (c) routing the additional retirement savings into a different vehicle (a taxable brokerage, where long-term growth is at least taxed at the preferential capital gains rates rather than as ordinary income; additional Roth conversions of traditional IRAs in low-income years; deferred compensation if available).
Feature 1: after-tax employee contributions permitted above the elective deferral limit. This feature must be explicitly enabled in the plan document. Not all 401(k) plans permit after-tax contributions; many of the older or smaller-employer plans treat the elective deferral limit as the only employee contribution category and do not provide for after-tax contributions. The Summary Plan Description is the document that confirms or denies this feature; the employee should request it from the plan administrator and search for “after-tax” or “voluntary after-tax” contributions.
Feature 2a: in-plan Roth conversion of after-tax balances, OR Feature 2b: in-service withdrawal of after-tax balances. The conversion-to-Roth step is the strategy’s value-producing mechanism, and it requires one of two specific plan features. The first option, in-plan Roth conversion, lets the employee convert the after-tax balance to Roth treatment inside the same 401(k) plan, frequently with automated conversion immediately after each contribution (a feature sometimes called “automatic in-plan Roth conversion” or “Roth in-plan rollover”). The second option, in-service withdrawal of after-tax balances, lets the employee withdraw the after-tax balance from the 401(k) while still employed and roll it into an external Roth Individual Retirement Account, where it is treated as Roth dollars going forward.
The two options are functionally similar but mechanically different. The in-plan Roth conversion keeps the balance inside the 401(k), which means the employee continues to be subject to the plan’s investment options and any plan-level restrictions. The in-service withdrawal moves the balance to an external Roth Individual Retirement Account, which gives the employee the full range of brokerage investment options but separates the balance from the 401(k)‘s creditor protection (Roth IRAs have weaker creditor protection than 401(k) accounts under federal law, though state-level protection varies).
The “automatic in-plan Roth conversion” variant is the gold-standard plan feature for executing the strategy. With automatic conversion enabled, each after-tax contribution is converted to Roth treatment within days of the contribution being made, before any meaningful earnings can accumulate on the after-tax balance. The conversion is essentially seamless and tax-free (because there is no earnings to be taxed at the conversion point).
The step-by-step process
For an employee whose plan permits both required features, the execution is straightforward.
Step 1: confirm the elective deferral and after-tax contribution rooms for the year. The elective deferral room is $24,500 (2026) minus what the employee has already contributed to the elective deferral category. The after-tax room is the overall $72,000 limit minus the employee’s elective deferral contributions, minus the employer contributions expected for the year. The employer contributions can be estimated from the prior year’s contributions if the match formula is unchanged.
Step 2: enroll in after-tax contributions through the plan’s contribution election system. The election is separate from the elective deferral election; the employee may need to specify a percentage of pay for after-tax contributions or a flat dollar amount per pay period. The election is typically reversible on a per-pay-period basis if the employee’s circumstances change mid-year.
Step 3: enable automatic in-plan Roth conversion (or schedule the in-service withdrawal frequency). With automatic conversion enabled, each after-tax contribution is converted to Roth immediately upon arrival in the plan. Without automatic conversion, the employee has to initiate the conversion manually, which is typically a once-per-quarter or once-per-year process; the frequency should be high enough to minimize the after-tax earnings that accumulate before each conversion.
Step 4: verify, at year-end, that the contributions and conversions executed correctly. The employee’s W-2 will show the elective deferral contributions; the after-tax contributions and conversions should appear on the plan’s year-end statement, typically with a separate line item for “after-tax employee contributions” and “in-plan Roth conversions”. Any discrepancy should be raised with the plan administrator before the tax filing deadline.
Step 5: report the in-plan Roth conversion on the tax return. The conversion produces a Form 1099-R from the plan, with the after-tax basis in Box 5 and the conversion amount in Box 1. With prompt automatic conversion, the taxable portion of the conversion (the earnings on the after-tax balance between contribution and conversion) is small to zero. With delayed manual conversion, the taxable portion can be meaningful.
The execution is straightforward enough that an experienced employee can complete the entire cycle in 15 minutes of plan administration per year, with the actual contributions happening automatically through payroll deduction. The complexity is upfront in verifying plan features and setting up the elections; the ongoing administration is minimal.
Tax consequences — the pro-rata rule on earnings
The single tax complication in the mega backdoor Roth strategy comes from the pro-rata rule on earnings that accumulate between the after-tax contribution and the conversion to Roth. The Internal Revenue Service treats the after-tax balance as having two components — the original after-tax contribution (the basis, which is already taxed and converts to Roth tax-free) and the earnings on that balance (which are pre-tax dollars and are taxed as ordinary income at the conversion).
The pro-rata calculation. If an employee contributes $35,000 in after-tax dollars, and at the time of conversion the after-tax balance has grown to $35,200 (a $200 earnings accrual), the conversion produces $200 of taxable income at the employee’s marginal rate. At a 32% marginal rate, the tax is $64. The conversion is otherwise tax-free.
The strategic implication: minimize the earnings accumulation between contribution and conversion. With automatic in-plan conversion, the earnings accumulation per contribution is minutes or hours, producing essentially zero taxable income at conversion. With manual quarterly conversion, the earnings accumulation could be one to three months of investment returns on the after-tax balance, producing a few hundred dollars of taxable income per year (a minor inconvenience but worth tracking). With manual annual conversion, the earnings accumulation could be a full year of investment returns, producing potentially thousands of dollars of taxable income (still much smaller than the conversion value, but worth converting more frequently to avoid).
The pro-rata rule does not affect the post-conversion Roth treatment. Once the after-tax basis is converted to Roth, the balance compounds tax-free and is fully tax-free on qualified withdrawal — the standard Roth tax treatment applies. The pro-rata rule applies only at the conversion point, on the earnings that accumulated before conversion.
Common employer plan limitations and workarounds
Several variations exist in how different employer plans implement (or fail to implement) the features required for the strategy.
Plans that permit after-tax contributions but cap them below the maximum. Some plans permit after-tax contributions but limit them to a percentage of pay that does not maximize the available room. An employee whose plan caps after-tax contributions at 10% of pay, at a $200,000 salary, is limited to $20,000 of after-tax contributions per year regardless of the actual after-tax room available under the $72,000 overall limit. The fix is either lobbying the plan sponsor to raise the cap (HR teams at large employers will sometimes adjust the cap in response to employee requests) or accepting the lower contribution and finding additional retirement savings outside the plan.
Plans that permit after-tax contributions but no conversion mechanism. This is the worst combination for the strategy because the after-tax contributions produce taxable earnings inside the plan with no Roth conversion pathway. The after-tax contributions are still useful (the basis remains untaxed at distribution), but the strategic value of the strategy is mostly lost. The fix is lobbying the plan sponsor to add the in-plan Roth conversion feature, which is a common-enough request that most major plan administrators (Fidelity, Vanguard, Schwab) support the feature in their standard product menu.
Plans that permit after-tax contributions and in-service withdrawals but only at specific ages. Some plans permit in-service withdrawals of after-tax balances only at age 59.5 or older, which makes the strategy useless for younger employees. The fix is the same: lobby the plan sponsor for an “in-service withdrawal at any age for after-tax sources” amendment to the plan document.
Plans that fully support the strategy. Google, Microsoft, Meta, Amazon, several major investment banks (Goldman Sachs, Morgan Stanley), and a meaningful share of the tech industry have plans that fully support the strategy, often with automatic in-plan conversion enabled by default. Employees at these firms can execute the strategy with no friction beyond the initial setup.
The exit pathway — what happens at retirement
The Roth balance produced by the mega backdoor Roth strategy is identical to any other Roth balance for tax purposes at retirement: tax-free withdrawal of contributions at any age, tax-free withdrawal of earnings after age 59.5 and after the five-year clock on the Roth account. The five-year clock starts on the date of the first Roth contribution to any Roth account the employee owns, not on each individual contribution; an employee with a Roth Individual Retirement Account they opened ten years ago has already satisfied the five-year clock for all subsequent Roth contributions, including mega backdoor Roth conversions.
The Roth balance can be rolled over to a Roth Individual Retirement Account at retirement (or earlier, with separation from service), giving the employee access to the full range of investment options at any custodian. The Roth Individual Retirement Account has no required minimum distribution during the account holder’s lifetime, allowing the balance to continue compounding tax-free indefinitely. The Roth Individual Retirement Account is also a uniquely favorable inheritance vehicle for non-spouse beneficiaries, who can stretch withdrawals over a ten-year window (post-SECURE Act) and benefit from the tax-free treatment during the inheritance window. The Roth IRA guide covers the five-year clock and qualified-distribution mechanics in detail, and the tax-advantaged hierarchy guide places the mega backdoor inside the broader account-funding sequence.
A worked example — ten years of mega backdoor Roth contributions
Consider Priya, a software engineer at a major tech employer, age 30, earning $220,000 in salary. Her 401(k) plan supports the full mega backdoor Roth strategy with automatic in-plan conversion enabled. Her annual contributions:
- Employee elective deferrals: $24,500 to traditional 401(k) (full deferral limit).
- Employer match: $13,200 (a 50% match on the first $13,200 of contributions, i.e., 6% of her salary).
- After-tax employee contributions: $34,300 ($72,000 overall limit minus $24,500 elective deferral minus $13,200 employer match).
- Automatic in-plan Roth conversion of the after-tax contributions: roughly $34,300 converted to Roth each year, with $0 to $50 in pro-rata earnings tax.
Over ten years, with the elective deferral and after-tax limits increasing at approximately 2.5% per year for inflation, Priya’s contributions roughly:
- Cumulative elective deferrals: $274,000 (to traditional 401(k)).
- Cumulative employer match: $148,000.
- Cumulative after-tax contributions converted to Roth: $384,000.
Assuming a 6% real return on investments, the balances at year 10:
- Traditional 401(k) (elective deferral + employer match): $558,000.
- Roth 401(k) (from mega backdoor Roth conversions): $507,000.
The Roth balance is essentially equivalent to having made an additional $507,000 of contributions to a Roth Individual Retirement Account, which is impossible under the $7,500 annual Roth Individual Retirement Account limit for Priya’s income (which exceeds the Roth Individual Retirement Account income cap anyway). The strategy has produced a Roth retirement asset that compounds tax-free for the next thirty-five years, worth multiples of the equivalent traditional retirement asset on a tax-adjusted basis.
The strategy does require Priya to commit $34,300 of post-tax cash to the after-tax contribution category each year, which at her income level is comfortable but not trivial. The cash flow is recoverable if her circumstances change — she can stop or reduce the after-tax contributions mid-year — but the balance accumulated up to that point continues to compound in Roth treatment.
Sources
- 2026 Internal Revenue Service limits for 401(k) plans (Section 415 overall limit, Section 402(g) elective deferral limit): Internal Revenue Service — 2026 Retirement Plan Limits (search for the current year notice).
- After-tax employee contribution rules and in-plan Roth conversion mechanics: Internal Revenue Service — Designated Roth Accounts and Internal Revenue Service — In-plan Roth rollover.
- Pro-rata rule on earnings at Roth conversion: Internal Revenue Service Notice 2014-54.
- Five-year rule on Roth contributions and earnings: Internal Revenue Service Publication 590-B.
- Plan-feature variation across major US employers: The White Coat Investor — Mega Backdoor Roth maintains a current view of which large employers support the strategy.
If a 401(k) plan rule on this page looks off against current plan documents, the Summary Plan Description from the specific plan is authoritative; let us know via contact and we will reconcile.
Quick answers
How do I know if my 401(k) plan supports the mega backdoor Roth?
Two features have to be present together: (1) the plan must permit after-tax (non-Roth, non-pre-tax) employee contributions above the elective deferral limit, and (2) the plan must permit either in-plan Roth conversion of those after-tax balances or in-service withdrawal of after-tax funds to an external Roth Individual Retirement Account. Request the Summary Plan Description from your plan administrator and search for "after-tax contributions" and "in-plan Roth rollover" or "in-service withdrawal." If either feature is missing, the strategy is not available regardless of your income.
How much can I contribute via the mega backdoor Roth in 2026?
The math is the Section 415 overall limit ($72,000 in 2026 for under-50 contributors) minus your elective deferrals ($24,500 if you max) minus your employer contributions. For an employee maxing the deferral with a $15,000 employer match, the available after-tax room is $72,000 − $24,500 − $15,000 = $32,500. With a smaller employer match, the room is larger; with a more generous match, the room is smaller. The figure scales with the employer match you actually receive, not with what the plan offers.
Does the mega backdoor Roth conversion trigger taxable income?
Only on the earnings that accumulated between the after-tax contribution and the conversion. The after-tax basis itself converts to Roth tax-free (you already paid tax on the contribution). With automatic in-plan conversion enabled, the conversion happens within days of the contribution and the earnings accumulation is essentially zero, so the conversion is functionally tax-free. With manual quarterly or annual conversion, the earnings accumulation can be larger — typically a few hundred dollars per year of taxable income at conversion, which is small but worth converting more frequently to minimize.
Is the mega backdoor Roth at risk of being eliminated by Congress?
It has been discussed in recent legislative cycles, most notably in 2021 when the original Build Back Better bill contained provisions to close the after-tax-to-Roth pathway. Those provisions did not pass into law, and as of 2026 the strategy remains fully available where the plan supports it. Future Congresses could revisit the question, so high earners who can use the strategy should execute it while available rather than defer; the lifetime tax-free compounding that results is large enough to make several years of execution worthwhile even if the pathway is closed later.
Educational content only. finbarrow is an independent editorial publication, not a licensed financial advisor, broker, tax preparer, or attorney. Verify rates and terms with the issuer or relevant regulator. See disclaimers and funding disclosures.